
RC4288 taxpayer relief request: how to ask the CRA to cancel penalties and interest
Short answer
An RC4288 taxpayer relief request asks the CRA to cancel or waive penalties and interest, not the tax itself. The CRA considers extraordinary circumstances such as serious illness, financial hardship, and its own errors or delays. A request can reach back 10 calendar years, can be made online in My Account or by mailing Form RC4288, and takes 16 months on average, according to the CRA.
- 01Form
- RC4288, Request for Taxpayer Relief
- 02What it can cancel
- Penalties and interest only, not tax
- 03Time limit
- 10 calendar years before the year of the request
- 04Average processing time
- 16 months (CRA figure)
- 05Federal Court deadline
- 30 calendar days after receiving a decision
- 06Quebec GST/HST and QST relief
- Revenu Québec form FP-4288-V, not RC4288
What does an RC4288 taxpayer relief request cover?
An RC4288 taxpayer relief request is how you ask the CRA to use its discretion to cancel or waive penalties and interest. The form's full name is RC4288, Request for Taxpayer Relief, Cancel or Waive Penalties and Interest. You can also make the same request online through your CRA account.
Relief never touches the tax you owe. If your return shows $4,000 of tax, that $4,000 stays. What can go away are the charges added on top, such as the late-filing penalty, instalment interest and arrears interest.
A worked example of what is at stake
Say you owed $4,000 on a return filed 3 full months late. The late-filing penalty is 5% of the balance ($200) plus 1% for each full month late ($120), for a total of $320. Arrears interest is added on top at the prescribed rate, which is 7% compounded daily for October to December 2026, the same as the previous quarter. A successful request could remove the $320 and some or all of that interest. The late-filing penalty page shows how the penalty grows for repeat late filers.
Situations the CRA considers for taxpayer relief
The CRA groups qualifying situations into three categories, and it also reviews other situations on their merits. Your request should say clearly which category applies to you and show how the event stopped you from meeting the deadline.
| Category | Examples | What can be relieved |
|---|---|---|
| Extraordinary circumstances | Flood or fire, postal strike, serious illness or accident, serious emotional distress such as a death in the immediate family | Penalties and interest |
| Actions of the CRA | Processing delays, errors in CRA publications, wrong information from the CRA, undue delays in an objection, appeal or audit | Penalties and interest |
| Inability to pay or financial hardship | Interest is a large part of the debt and a reasonable payment plan is not possible; paying would cut access to food, medical care, transport or shelter | Interest, generally not penalties |
Events affecting your authorized representative can also count, for example if the person who prepared your return had a serious illness at filing time.
What a CRA penalty waiver will not cover
- The tax assessed on your return
- Penalties or interest outside the 10-year window
- Amounts the CRA has no legal authority to cancel or waive
- Bank fees and similar administrative charges
- Mistakes by a third party, except in exceptional cases
The 10-year limit on CRA interest relief
You can only ask about penalties and interest tied to the 10 calendar years before the year you make the request. For penalties, the tax year must end within the window. For interest, the interest must have built up during the window, even if the tax year itself is older.
| Year you submit the request | Oldest penalty year you can include |
|---|---|
| 2026 | Tax years ending in 2016 or later |
| 2027 | Tax years ending in 2017 or later |
If you are close to the edge of the window, submit before December 31. A request sent in January loses one year of coverage. Right now that matters for 2016: penalties for tax years ending in 2016 can be included only in a request made by December 31, 2026.
How to apply with the taxpayer relief form or online
You can apply online or by mail. Choose the route that lets you send all of your supporting documents together.
- Online (individuals): sign in to My Account, go to Accounts and payments and choose Request relief of penalties and interest. A representative can do the same in Represent a Client.
- Online (businesses): in My Business Account or Represent a Client, select the program and account involved, such as GST/HST, and choose Request relief of penalties and interest.
- By mail: fill in Form RC4288 and send it to the designated office listed on the last page of the form, based on where you live.
Documents that support each type of request
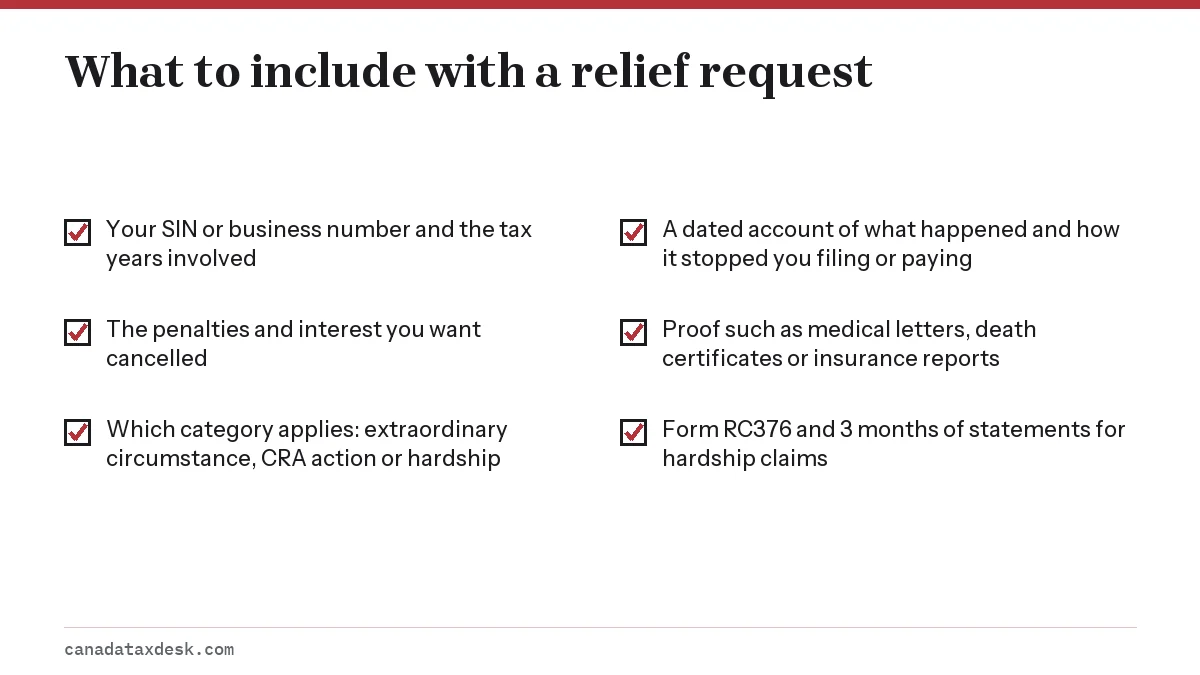
The CRA asks for a detailed, complete and accurate description of your circumstances and all relevant supporting information. For hardship requests, include Form RC376, Taxpayer Relief Request, Statement of Income and Expenses and Assets and Liabilities for Individuals, plus your bank and credit card statements for the most recent 3 months. For illness or a death, documents such as a doctor's letter with treatment dates or a death certificate show the timing. For CRA errors, include the letters or notes of calls that show the delay.
RC4288 or FP-4288 in Quebec?
Form RC4288 covers penalties and interest charged by the CRA. In Quebec, Revenu Québec administers the QST and, for most businesses, the GST/HST, and it has its own form: FP-4288-V, Application for the Cancellation or Waiver of GST/HST- and QST-Related Interest or Penalties, or of QST-Related Charges (FP-4288 in French). Interest and penalties on your Quebec provincial income tax return are also decided by Revenu Québec, so ask Revenu Québec, not the CRA, to cancel those. A selected listed financial institution with GST/HST or QST matters uses CRA Form RC7288 instead of RC4288.
After you apply: decisions, second review and court
The CRA reports an average processing time of 16 months for relief requests. You can follow the file with the Progress Tracker on the Overview page of My Account. If the penalty is tied to an assessment under objection or appeal, no final decision is made until that dispute is settled.
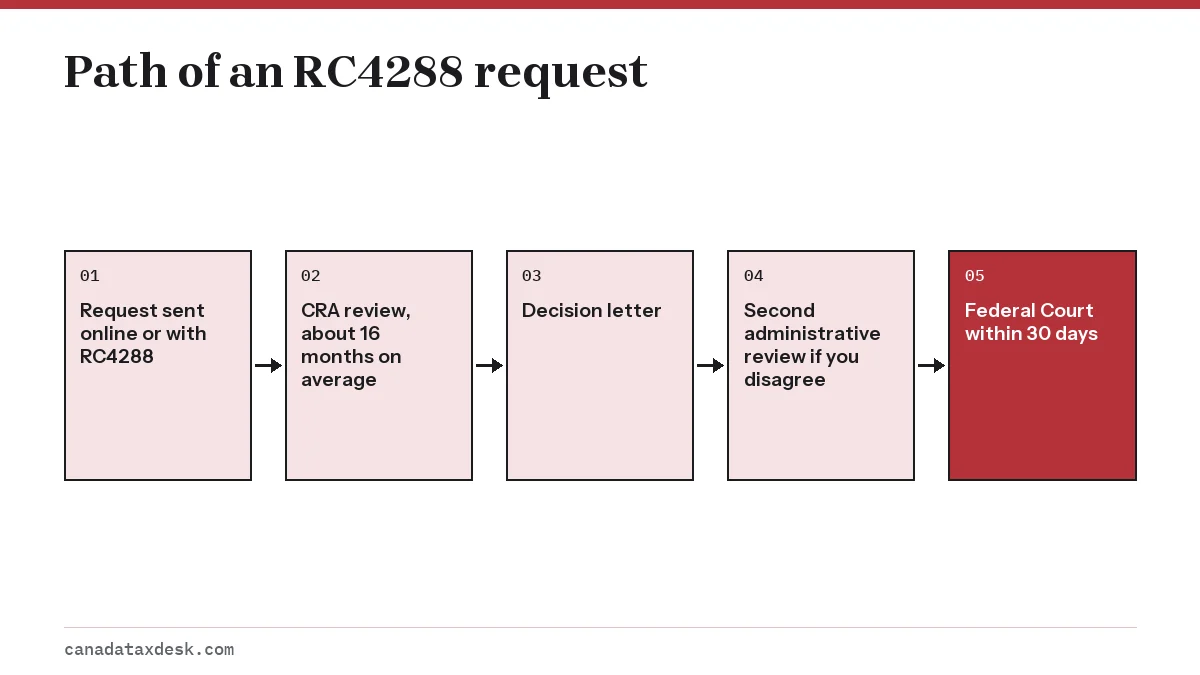
You will receive a letter saying the request was approved, partly approved or denied. If you disagree, ask for a second administrative review, giving your reasons and supporting documents. None of the officials from the first review take part, so add any new facts or documents you did not send the first time.
You can apply to the Federal Court for judicial review within 30 calendar days of receiving a CRA relief decision. The CRA recommends asking for the second administrative review first.
Relief is only one fix. If the penalty came from a registered account, the rules are different: see TFSA over-contribution penalty and RRSP over-contribution. If you have not filed yet, file first; the guide to filing a tax return covers every method, and a payment arrangement can stop collection pressure while you wait.
Step by step
Confirm the charges
Check your notice of assessment or statement of account in My Account for the exact penalties and interest and the tax years involved.
Check the 10-year window
Make sure each tax year ends within the 10 calendar years before the year you submit.
Gather evidence
Collect medical letters, death certificates, disaster reports, CRA correspondence or Form RC376 and bank statements, depending on your reason.
Submit the request
Use Request relief of penalties and interest in My Account, or mail Form RC4288 to the office on the last page of the form.
Track and respond
Follow the Progress Tracker, answer any CRA follow-up, and ask for a second review if you disagree with the decision.
Common questions
What is CRA taxpayer relief?
It is the CRA's power to cancel or waive penalties and interest when events beyond your control, financial hardship or CRA errors caused them. It does not reduce the tax itself.
How far back can I ask for taxpayer relief?
Ten calendar years before the year you submit. A request made in 2027 can cover penalties for tax years ending in 2017 or later.
How long does a CRA taxpayer relief request take?
The CRA's published average is 16 months, and it says some cases take more or less time. Requests tied to an objection or appeal are not decided until that dispute is resolved.
Can I write a letter instead of using Form RC4288?
The CRA directs individuals to the online request in My Account or to Form RC4288 by mail. Using one of those makes sure you give the account number, tax years and reasons the reviewer needs.
What is CRA Form RC376?
Form RC376, Taxpayer Relief Request – Statement of Income and Expenses and Assets and Liabilities for Individuals, is how an individual shows financial hardship. Send it with your relief request, along with documents such as mortgage statements and your bank and credit card statements for the most recent 3 months.
What is form FP-4288?
FP-4288-V is Revenu Québec's form for asking it to cancel or waive GST/HST- and QST-related interest or penalties, or QST-related charges. Use it for amounts Revenu Québec administers; use RC4288 or My Account for amounts charged by the CRA.
Does the CRA forgive penalties for a first-time late filing?
Being late for the first time is not a listed reason on its own. The CRA looks for a qualifying cause such as serious illness, a disaster, hardship or a CRA error, so explain the cause and include proof.
What if my taxpayer relief request is denied?
Ask for a second administrative review with any new information. You can also apply to the Federal Court for judicial review within 30 calendar days of receiving a decision, though the CRA recommends the second review first.
Sources
- CRA: Cancel or waive penalties and interest canada.ca
- CRA: Taxpayer relief, who can apply canada.ca
- CRA: Taxpayer relief, how to apply canada.ca
- CRA: Taxpayer relief, after you apply canada.ca
- CRA: Form RC4288 canada.ca
- CRA: Late-filing penalty canada.ca
- Revenu Québec: Form FP-4288-V revenuquebec.ca
- CRA: Prescribed interest rates, October 1 to December 31, 2026 canada.ca
We check figures against these official pages. Rules change; confirm anything that affects a deadline or payment with the agency before you act.
Tell us what happened
Describe your situation and our editors will use it to improve this guide. If you leave your email, we may reply with a pointer to the right page or official contact. We never share your details.
Related guides
 How to File a Tax Return in Canada: Complete Guide
How to file a tax return in Canada: collect your slips and receipts, pick a filing method (certified software with NETFILE, a Sim…
TFSA Over-Contribution Penalty: How to Fix It and Get Relief
The TFSA over-contribution penalty is a tax of 1% per month on the highest excess amount in your TFSA in each month, for as long…
RRSP Over-Contribution Penalty: The $2,000 Buffer and T1-OVP
An RRSP over contribution is only penalized when your unused contributions exceed your RRSP deduction limit by more than $2,000.…
CRA Payment Arrangements: How to Set Up a Tax Payment Plan
CRA payment arrangements let you pay a tax debt in instalments you agree with the CRA. If you owe $1,000 or more in personal inco…